Whether pellet production is profitable depends on local raw-material cost, electricity, labor, saleable output, product selling price, operating utilization, packaging, maintenance and other site-specific costs. Calculate production cost per tonne from your own project inputs before estimating an operating margin.
This guide explains a reusable calculation method. It does not provide current market prices, a project quotation or a TCPEL production or profit guarantee. The original article illustration dated 2023 is not evidence of current prices or measured project results.
What Cost per Tonne Actually Means
Choose one reporting period, one currency and an agreed production boundary. Define M as the net tonnes of saleable pellets produced within that period and boundary, and C as the production costs attributed to that output. A tonne (t) means 1,000 kg. For M greater than zero:
Production cost per tonne = C ÷ M
State whether the boundary covers the pellet mill alone or the complete process, including any preparation, drying, cooling, screening and packing. Separate operating expenditure from allocated depreciation, and list exclusions. Comparing two costs per tonne is meaningful only when their output, quality, moisture, currency and cost scopes are comparable.
Define Saleable Pellet Output
Use acceptable finished-pellet net mass at the stated final moisture and quality, not wet raw-material feed, pellet-mill discharge or bag gross weight. Do not count internal fines and reprocessed material as new finished output each time they pass through the machine. Reconcile opening and closing raw-material, work-in-progress and finished-product inventories so costs and output belong to the same period.
For planning, expected saleable tonnes = expected saleable output (t/h) × productive operating hours. Scheduled hours are not automatically productive hours. Use project-specific allowances for stoppages and quality losses, without treating an assumed rate as guaranteed output. The guide to sizing a pellet line from daily production targets explains that distinction.
For equipment context, TCZL560 has a 90 kW motor and a reference capacity range of 1–1.5 t/h. These machine references are not measured complete-line electricity use or guaranteed saleable line output. Use actual records or a clearly identified project estimate for the cost-model denominator.
Raw-Material Cost per Tonne
Use the cost of material actually consumed for the period, rather than treating all purchases placed in storage as consumption. Record the local purchase price, delivery basis, material form, moisture basis and preparation losses.
Raw-material cost per tonne of pellets = attributed raw-material consumption cost ÷ M
If material is bought by wet tonne, a simple single-material calculation is wet tonnes consumed × price per wet tonne ÷ M. Do not apply a universal wet-feed-to-pellet ratio. Water removal, rejected contaminants and dry-material losses change the relationship; confirm the actual material balance and avoid mixing wet-basis and dry-basis prices.
Electricity and Other Energy Costs
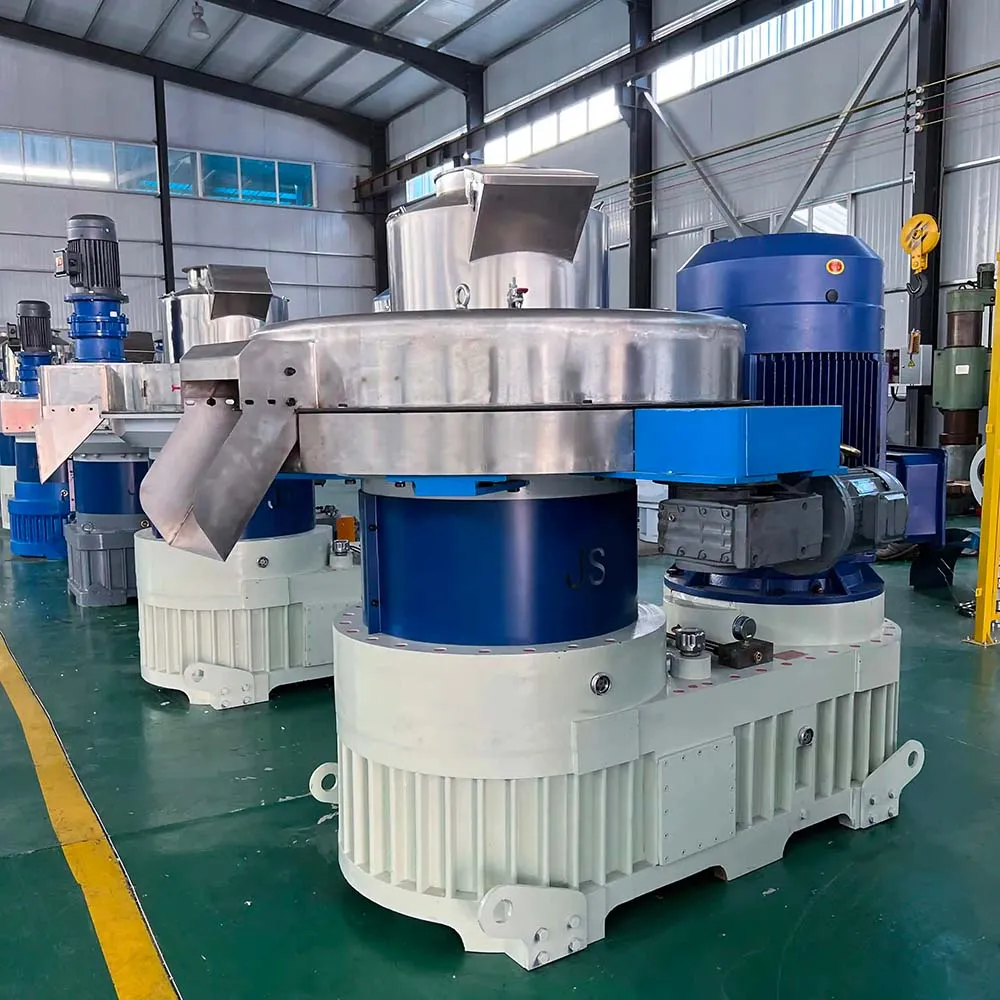
kW is power; kWh is energy measured over time. A 90 kW motor nameplate is not a fixed electricity consumption figure for every operating hour or for the complete line. A load-factor assumption is an estimate, not a measured TCPEL performance value.
Specific electricity use (kWh/t) = metered electricity during the period (kWh) ÷ M
Electricity cost per tonne = electricity charges attributed to the agreed process and period ÷ M
For a simple energy-only tariff, the numerator is metered kWh × local price per kWh. Include or separately identify demand, standing and time-of-use charges where applicable. Record dryer fuel or purchased heat separately when used; an electricity-only figure is not total energy cost.
Use How to Calculate Pellet Production Electricity Use per Tonne for meter boundaries, acceptable finished output and rework treatment. The U.S. Energy Information Administration explanation of electricity units distinguishes power from energy.
Labor, Consumables and Other Production Costs
Use current local records or explicitly labeled planning assumptions. For each category, divide the cost attributed to the same period and process by M. The following checklist defines inputs; it is not a list of TCPEL fixed running costs.
| Cost category | Input and calculation boundary |
|---|---|
| Labor | Wages and applicable employment costs for the people assigned to the process. Include paid nonproductive time in the chosen cost scope. Identify owner labor separately if it has not been costed. |
| Consumables and spare parts | Use replacement cost ÷ saleable tonnes produced during usable life, or a consistent period allocation. Use supported service-life assumptions, not a universal ring-die lifetime. |
| Maintenance | Actual or clearly budgeted maintenance labor, service and materials. Exclude consumables already counted under spare parts. |
| Packaging | Bags, closures, pallets and other included packing materials. Bag and pallet mass do not increase net saleable pellet tonnes. |
| Factory overhead | Rent and relevant factory services allocated consistently to this process. Explain shared-facility allocations and avoid charging the same utility twice. |
| Depreciation | The equipment or facility depreciation allocated to the period under the project’s accounting policy. Do not also charge the full equipment purchase price as a production cost for that period. |
| Other project-specific costs | Include or explicitly exclude applicable quality control, waste handling, insurance, local compliance and other site costs. Keep transport and selling costs consistent with the selling-price boundary. |
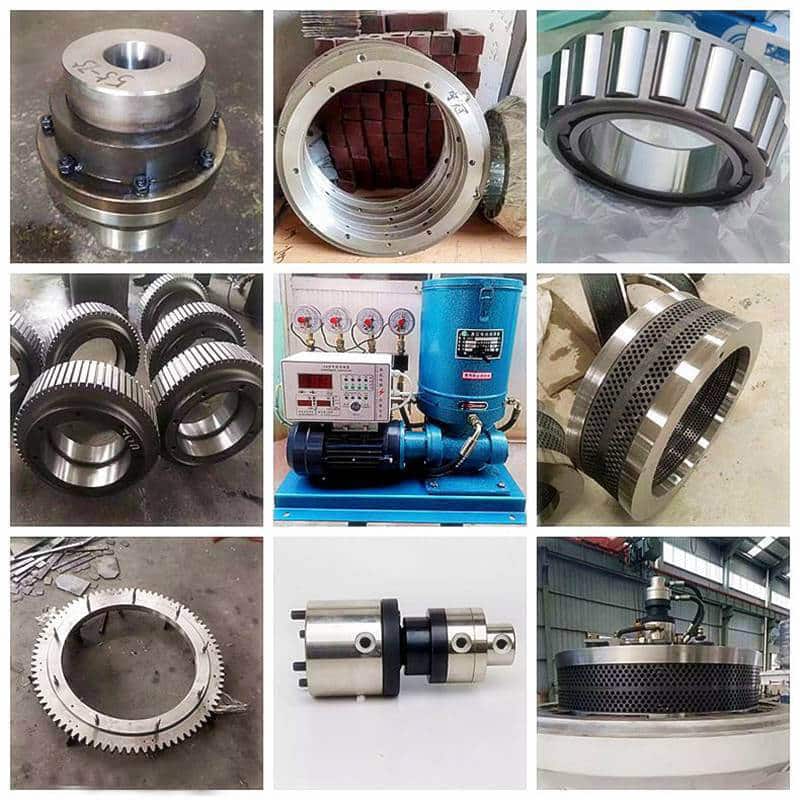
Actual consumable life depends on material, abrasiveness, operating conditions, operation and maintenance. Obtain suitable replacement prices and service assumptions for the actual equipment. A spare-parts allowance is not a lifetime guarantee.
Total Production Cost and Operating Margin
Total production cost per tonne = sum of all included production costs for the period ÷ M
Label any partial subtotal clearly. A model containing depreciation is not a cash-cost-only model. Check that spare parts, maintenance, energy and overhead have not been counted twice.
Let P be selling price per tonne on the same product, packaging, delivery and tax basis as the cost model. The calculation is:
- Margin per tonne = P − total production cost per tonne
- Hourly gross operating margin = margin per tonne × saleable pellet output (t/h)
- Daily gross operating margin = margin per tonne × saleable pellet output (t/h) × actual productive hours per day
- Annual gross operating margin = representative daily gross operating margin × actual operating days
Here, gross operating margin means the difference under the stated cost scope, not net company profit, EBITDA or a guaranteed return. The annual multiplication is only a planning approximation when daily conditions can reasonably represent the year. Use actual period revenue, production, sales and inventory records for an operating business.
If not already included, allow for tax, finance costs, sales expense, administration, insurance, downtime, inventory effects, transport, packaging, quality losses, working-capital requirements, local compliance and other project-specific costs. Working-capital funding also needs a separate cash-flow check. Do not deduct a cost twice or treat unsold production as realized sales revenue.
Illustrative Calculation Only
ILLUSTRATIVE ASSUMPTION: one hypothetical period produces and sells 100 t of acceptable pellets. The included production costs are 10,000 currency units, and selling price is 130 currency units/t on the same supply basis. All inputs are assumptions; none is a current market quotation.
- Production cost = 10,000 ÷ 100 = 100 currency units/t.
- Margin = 130 − 100 = 30 currency units/t.
- Period gross operating margin under this cost scope = 30 × 100 = 3,000 currency units.
If those 100 t are produced and sold over 10 productive days of 8 hours at an assumed 1.25 t/h saleable output, the same arithmetic gives 37.5 currency units/hour and 300 currency units/day. This rate is a hypothetical input, not a TCZL560 or complete-line capacity claim.
The example is for calculation method only and is not a current quotation, market-price forecast or TCPEL performance or profitability guarantee.
Project Input Checklist
- Raw-material purchase and delivery cost, moisture basis, preparation loss and actual consumption.
- Required finished-pellet quality, moisture and saleable output; productive hours and operating days.
- Actual or expected metered electricity, applicable tariff and any drying fuel or heat costs.
- Labor requirement, local wages and applicable employment costs.
- Consumable replacement costs and supported usable-life assumptions; maintenance allowance.
- Packaging, factory overhead, depreciation and other local costs, with exclusions identified.
- Expected saleable pellet price, delivery basis, sales volume and inventory assumptions.
Why Profitability Varies by Project
Market demand alone does not establish a factory’s margin. Obtain current local input prices, confirm the product specification and sales conditions, and compare realistic productive output with the costs inside the chosen boundary. Recalculate when moisture, material supply, utilization, energy price or product selling price changes.
For investment planning, keep the equipment quotation separate from production-cost accounting. Use Compare Complete Wood Pellet Production Line Quotations to check included equipment, interfaces and responsibilities. Review TCPEL’s configurable pellet production lines for project scope, then contact TCPEL with your raw material, moisture, required finished output, operating plan and site conditions. Equipment recommendations and any performance commitments require project-specific confirmation.